Evidence Before Cover: Assembling an Asbestos File UK Insurers Will Accept
Photo: Betty Longbottom, CC BY-SA 2.0, via Wikimedia Commons
Commercial property insurance is, at its heart, a transaction in information. The underwriter is not simply pricing the building; they are pricing the uncertainty that surrounds it. For UK premises built before the turn of the millennium, asbestos is one of the most persistent sources of that uncertainty. Insurers have long asked whether asbestos is present. The more searching question now is how it is being managed, and whether the owner or facilities team can prove it.
That shift matters at renewal, and it matters even more after a loss. A well-ordered asbestos file does not make a property risk-free, but it does make the risk legible. A thin or inconsistent file does the opposite: it suggests that the dutyholder may not know what is in the building, and that a future claim could become a dispute about what should have been known.
From presence to management
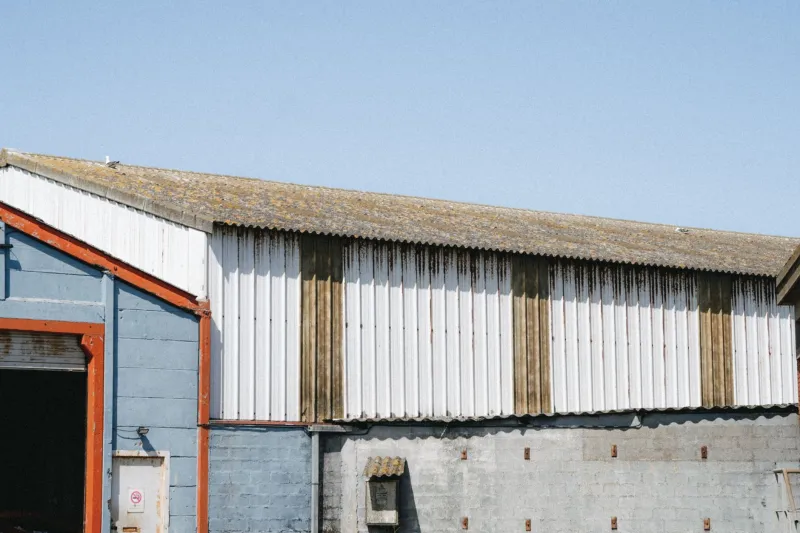
Asbestos-containing materials remain widespread in UK commercial stock. Their presence is not, in itself, a barrier to cover. Underwriters are accustomed to ageing buildings, service risers, ceiling voids and institutional estates where asbestos has been identified and is being managed in place. The concern arises where there is no reliable register, no clear management plan, or no evidence that condition and location are being kept under review.
Brokers are reflecting this in the questions they put to clients. A renewal submission may now be expected to include more than a passing reference to an old survey. Insurers vary in how prescriptive they are, and requirements will differ according to property type, occupancy, claims history and the appetite of the market at the time. There is no single mandatory document set. There is, however, a recognisable pattern in what credible evidence looks like.
What underwriters typically want to see
Underwriters generally want assurance that the duty to manage asbestos has been addressed in a way that is proportionate to the property. In practice, that usually means a current asbestos management survey and a register that identifies materials, locations and condition. A management plan should set out who is responsible for what, how works are controlled, and when materials will be reinspected.
The supporting evidence matters as much as the headline documents. Insurers and their risk engineers may look for condition assessments, priority ratings, records of removal or encapsulation, and a clear schedule for reinspection. Where areas could not be accessed during the survey, a no-access log and a plan for resolving those gaps will carry more weight than a report that quietly implies the whole building was seen.
Contractor controls are another common theme. A permit-to-work system, asbestos awareness arrangements, induction records and clear procedures for emergency repairs all help to show that the management plan operates on site rather than only in a filing cabinet. If refurbishment or demolition works are planned, the insurer may also expect a refurbishment or demolition survey before those works begin.
When the file is thin: water, fire and contractor disturbance
The practical consequences of weak records tend to surface after an unexpected event. A burst pipe brings down a ceiling in a circulation area. An emergency contractor attends out of hours and cuts into a board that was never recorded. A small fire leads to debris clearance and a disturbance of materials in a service void. In each case, the insurer will ask not only what happened, but what the insured knew and what controls were in place.
Commercial property policies commonly include conditions requiring the insured to take reasonable precautions to prevent loss and to comply with statutory obligations. Whether a particular omission breaches those conditions will always depend on the facts. But a missing register or an out-of-date management plan makes it harder to demonstrate that reasonable steps were taken. That can lead to a dispute over the extent of cover, a reduction in an indemnity, or an argument about uninsured costs such as specialist cleaning, business interruption, legal defence or contractor claims.
The point is not that every claim involving asbestos will be refused. It is that the quality of the asbestos file can influence how smoothly a claim is handled and how much of the loss is met. Insurers are also entitled to clear answers when they ask material questions at proposal or renewal. An incomplete or misleading answer about asbestos management can create problems that are entirely separate from the physical condition of the building.
Assembling a credible evidence pack
A credible pack does not need to be elaborate. It needs to be accurate, current and easy to navigate. The following checklist is a practical starting point for owners and facilities managers preparing for renewal or responding to an insurer’s request.
- The current asbestos survey report, with the survey type, date, scope and any limitations clearly stated.
- The asbestos register and management plan, showing named responsibilities and the arrangements for controlling works.
- Condition assessments and priority ratings for identified materials, together with the reinspection schedule and the date of the last inspection.
- Records of removal, encapsulation or remediation, including completion documentation and any clearance evidence.
- A no-access register and a documented plan for accessing those areas.
- Contractor procedures, permits-to-work, induction records and asbestos awareness arrangements.
- Emergency procedures for damage, disturbance or discovery of previously unrecorded materials.
- A short cover sheet that summarises the property, the survey position, the management arrangements and any outstanding actions.
Presentation is part of the evidence
A common weakness is a pack that contains the right documents but cannot be used. Files with inconsistent property names, undated summaries or reports that do not match the current site layout create doubt. Underwriters and risk engineers are not usually looking for a perfect estate; they are looking for evidence that the dutyholder understands the property and is managing it coherently.
An index, a one-page summary and a clear note of any open actions will often do more for confidence than a large unindexed bundle. The pack should also be refreshed after works, not merely at renewal. If a removal project has been completed or a previously inaccessible void has been surveyed, the file should say so.
Insurance is not a substitute for asbestos compliance, and a good asbestos file is not a guarantee of cover or of a claim being paid. It is, however, increasingly part of the evidence base that insurers use to understand a property. For dutyholders, the discipline of keeping that evidence in order supports both regulatory compliance and commercial resilience. DG Asbestos Compliance works with property owners and facilities teams to ensure that survey findings, management records and remediation evidence are assembled in a form that stands up to scrutiny — at renewal and after an incident.